← Back home

Home services

Verified accounts for US home services businesses taking online payments

Plumbers, electricians, cleaners, landscapers and every crew that works at a customer's door: how a verified account turns deposits, same-day payment and refunds into a routine instead of a chase.

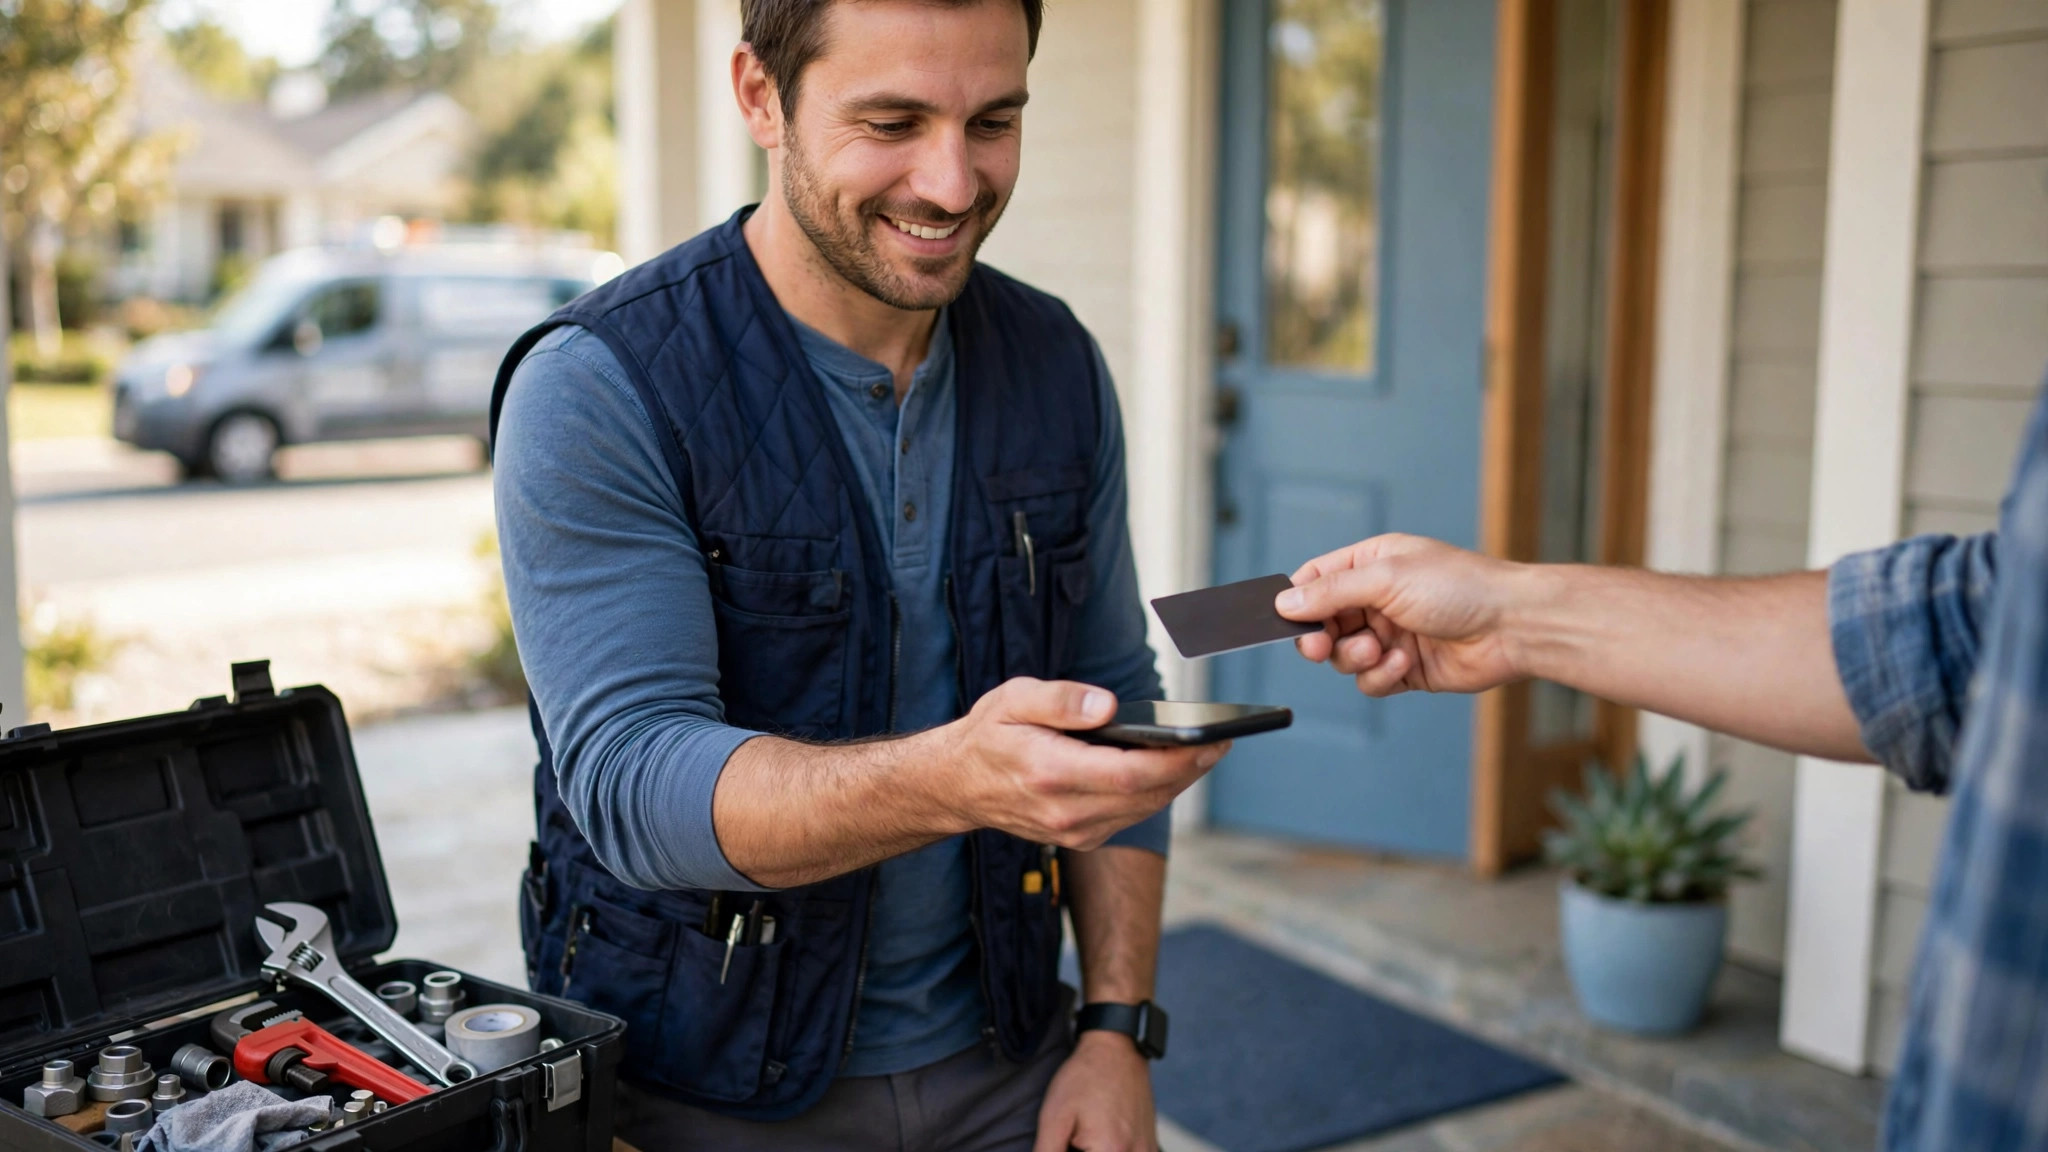
Home services technician taking a card payment at a customer's front door

The short version

Take a deposit when the job is booked, collect the balance the day the work is done, and keep every payment tied to a job, a customer and a date. A verified account makes all three easy — and it is the verification, not the card reader, that keeps payouts flowing and disputes rare.

Why home services businesses take payments online now

A plumber finishes a repair, an electrician rewires a panel, a cleaning crew leaves a spotless kitchen — and then comes the awkward part: getting paid. For years, home services ran on checks left on the counter and invoices that sat unpaid for weeks. That is changing fast. Customers now expect to tap, click or pay from a link the same day the work is done, and the businesses that make payment easy get paid faster, argue less about money, and book more repeat work.

A verified account sits at the centre of that change. Verification is the process where a payment platform confirms who the business is — its legal name, its owner, its bank account — before it lets the business take card payments. Once verified, the business can send payment links, take cards on a phone at the front door, and receive payouts on a predictable schedule instead of chasing checks. The verification step matters because platforms treat verified businesses differently: higher trust, fewer surprise holds, and a support team that can actually find the account when something goes wrong.

This guide walks through the whole flow for a home services business: deposits before the job, payment on the day, refunds when things go sideways, and the records that keep tax season calm. It is written for owners of small crews — plumbing, electrical, HVAC, cleaning, landscaping, pest control, painting and handyman work — who want a payment setup that works from the truck, not just from a desk.

Start with a deposit, not a handshake

The single biggest improvement most home services businesses can make is collecting a deposit before the job starts. A deposit does three things at once. It confirms the customer is serious, which cuts no-shows and last-minute cancellations. It covers materials, so the business is not out of pocket before the first hour of work. And it creates a paper trail that ties the customer, the job and the payment together from the beginning.

A common pattern that works well is a deposit of part of the quoted price when the job is booked, with the balance due on completion. The exact split depends on the trade: materials-heavy jobs like HVAC installs or re-piping usually justify a larger upfront share, while a one-off cleaning visit may only need a small booking deposit. Whatever the split, put it in writing on the quote before the customer pays — the amount, what it covers, and whether it is refundable if the customer cancels. A deposit that surprises the customer is a dispute waiting to happen.

Online payment makes deposits painless. The business sends a payment link by text or email, the customer pays with a card in under a minute, and both sides get a receipt automatically. Compare that with the old way: mailing a check, waiting for it to clear, and then discovering the job date has already passed.

Getting paid on the day the work is done

The best time to collect the balance is the moment the work is finished, while the customer is standing next to the result. A verified account gives the business three practical ways to do that. The first is a card reader or a tap-to-pay phone at the front door: the customer taps a card or phone, the payment clears into the account, and the receipt goes out by text before the technician leaves the driveway.

The second is a payment link sent the moment the job is marked complete. This suits jobs where the customer is not home — a landscaper finishing a yard, a cleaner leaving after a scheduled visit. The link carries the exact amount and the job reference, so there is no confusion about what is being paid for. The third is an invoice, which suits larger jobs with staged payments: a deposit, a mid-job payment when materials arrive, and a final payment on completion. Invoices are slower, so reserve them for jobs where the amount or the staging genuinely needs one.

Whichever method is used, the rule is the same: send the request the same day. Every day a payment request waits, the chance it gets paid promptly drops. Customers are not usually avoiding payment — they are busy, and the job slips down their list. A same-day request with a clear amount and a one-tap link removes the friction. Many businesses also set a simple internal habit: no technician leaves a site without either a payment or a payment link sent. That one habit alone is often worth more than any new marketing.

What verification changes for a home services business

Verification sounds like paperwork, and it is — but it is paperwork with a payoff. Platforms ask for the business's legal name, its tax identification number, the owner's identity, and the bank account where payouts should land. They check that the name on the account matches the name on the bank account and that the address is real. For a sole trader, that may mean a personal tax ID and a personal bank account; for an LLC, it means the company registration and the business bank account.

The checks exist because payment platforms carry the risk of every transaction they process. If a customer disputes a charge, the platform is in the middle. A verified business is a known business, so the platform can resolve disputes faster and is less likely to freeze funds while it investigates. Unverified accounts face the opposite: lower limits, slower payouts, and holds that arrive at the worst possible moment — usually during the busiest week of the season.

There is one habit that prevents most verification trouble: keep the business details consistent everywhere. The legal name, the address and the phone number should match across the payment platform, the bank account, the website and the business listings. When a platform asks to re-verify — and platforms do, usually once a year or after a change of details — having one consistent set of records makes the process a short form instead of a week of back-and-forth. Keep the core documents in one folder: registration, tax ID letter, a recent bank statement and a proof of address, all current.

Refunds, disputes and the chargeback you can avoid

Every home services business will face a refund request eventually: a customer who is unhappy with the result, a job that ran over, or a scheduling mix-up that left someone waiting. How the business handles it decides whether it becomes a small cost or a chargeback — the customer asking their bank to reverse the payment, which costs the business the money plus a fee and a mark on its record.

The cheapest refund is the one the business issues itself, quickly and calmly. When a customer raises a problem, the first step is to listen and look at the job: photos from the day, the quote, and any messages exchanged. If the work genuinely fell short, offer to fix it first — most customers would rather have the job done right than their money back. If a fix is not possible, a partial refund tied to the specific shortfall is usually fairer than a full refund, and it should be explained in plain terms in writing.

Chargebacks happen most often when the customer feels ignored. A customer who cannot reach the business, or who gets no answer for days, turns to their bank because it is the only route left. So the real chargeback prevention is responsiveness: answer within a business day, acknowledge the issue even before it is resolved, and keep every message about the job in one place.

Keeping the paper trail clean

Home services businesses live or die by their records. Every payment — deposit, balance, refund, tip — should carry the same three details: who paid, which job it was for, and the date. When those three details are attached automatically by the payment platform, reconciling the books becomes a monthly routine instead of an annual panic. The business owner should be able to open any month and see every job, every payment and every refund without digging through text messages.

That discipline matters most at tax time. The income a business reports should match what its payment platforms report, and the expenses — materials, fuel, tools, subcontractor payments — should be recorded as they happen, not reconstructed from memory in April. A simple monthly habit works: at the end of each month, download the platform statement, match it against the job list, and file both together. Thirty minutes a month saves days of stress later, and it gives the accountant a clean set of numbers instead of a puzzle.

It also protects the business when a customer questions a charge months later. A receipt with the job address, the date, the amount and the payment method ends most arguments in one message. Without it, the business is relying on memory — and memory loses arguments.

Security habits for a crew that works on the road

A home services team works from trucks, customer driveways and kitchen tables, not from a locked office. That makes a few simple security habits worth more than any single piece of software. The first is to keep the payment account on as few devices as possible, and to make sure every device that touches it has a screen lock and the platform's app updated. A phone left on a job site with the payment app open is an open door.

The second is two-factor authentication on the payment account and on the email address behind it. The email address matters as much as the account itself: if someone takes over the email, they can reset the payment password. Use a strong, unique password for the email, turn on two-factor authentication, and never share the login with the whole crew. If team members need to take payments, give each of them their own login or their own card reader where the platform supports it, rather than sharing one password across the team.

The third habit is about what the business shares. Never send full card numbers or bank details by text or email, and never ask a customer to do so either. Payment links exist precisely so that sensitive details never pass through a chat thread. And when a team member leaves, remove their access the same day — logins, card readers and any shared devices. It takes five minutes, and it is the kind of thing that only becomes urgent after it is too late.

Choosing a setup that fits your trade

Not every home services trade needs the same setup. A cleaner or landscaper doing many small jobs a week benefits most from speed: tap-to-pay at the door and payment links for customers who are not home. A plumber or electrician doing fewer, larger jobs benefits most from staged invoicing and deposits that cover materials. An HVAC installer may need all three: a deposit at booking, a payment when equipment arrives, and a final payment on completion.

Recurring services deserve special attention. Weekly cleaning, fortnightly lawn care and monthly pest control are the steadiest income a home services business can have, and they are also the easiest to lose to a missed payment. A standing payment arrangement — a card on file with the customer's permission, charged on the same day each cycle — removes the monthly chase entirely. Always confirm the arrangement in writing, state the amount and the day it will be charged, and make it easy for the customer to pause or cancel.

Finally, match the setup to the business's real volume rather than its ambitions. A one-person operation does not need the same tools as a ten-truck fleet. Start with one verified account, one way to take deposits, and one way to collect on the day. Add invoicing or recurring billing only when the job volume makes it necessary. The goal is a setup the owner can run from the truck without a second thought — because the setup that gets used every day beats the perfect setup that nobody opens.

Before you send a deposit link

  • Quote the job in writing with the total, the deposit amount and what it covers.
  • State whether the deposit is refundable and under what conditions.
  • Use the customer's legal name and the job address on the quote and the link.
  • Send the link from the business number or email the customer already knows.

On the day the job is done

  • Walk the customer through the finished work before asking for payment.
  • Take a photo of the completed job and keep it with the job record.
  • Send the payment link or take the card payment before leaving the site.
  • Confirm the receipt arrived and the amount matches the quote.

Warning signs worth fixing this week

  • A customer insists on paying only in cash with no receipt — you have no proof the job was paid for.
  • A payment link you did not send arrives asking the customer to pay a different amount.
  • Your platform asks for re-verification and you keep putting it off — holds follow.
  • One team member knows every password for the business account.
  • Refunds are handled from memory instead of the platform, with no record kept.
  • The business bank account name does not match the name on the payment account.

Real verification

A verified business name, tax ID and bank account — the foundation every payment rests on.

Secure by default

Two-factor authentication, unique passwords and payment links instead of card numbers in chat.

A clean record

Every payment tied to a job, a customer and a date — the record that settles disputes fast.

Ready to get paid without the chase?

A verified account is the starting point for deposits, same-day payments and clean records. Ask us anything before you set yours up.