← Back home

Small business guides

Verified accounts for US coffee shops taking online orders and tips

Online orders, pre-orders and digital tips all flow through the same payout rails. Here is how a verified account keeps the money on schedule, the tips fair, and the records clean.

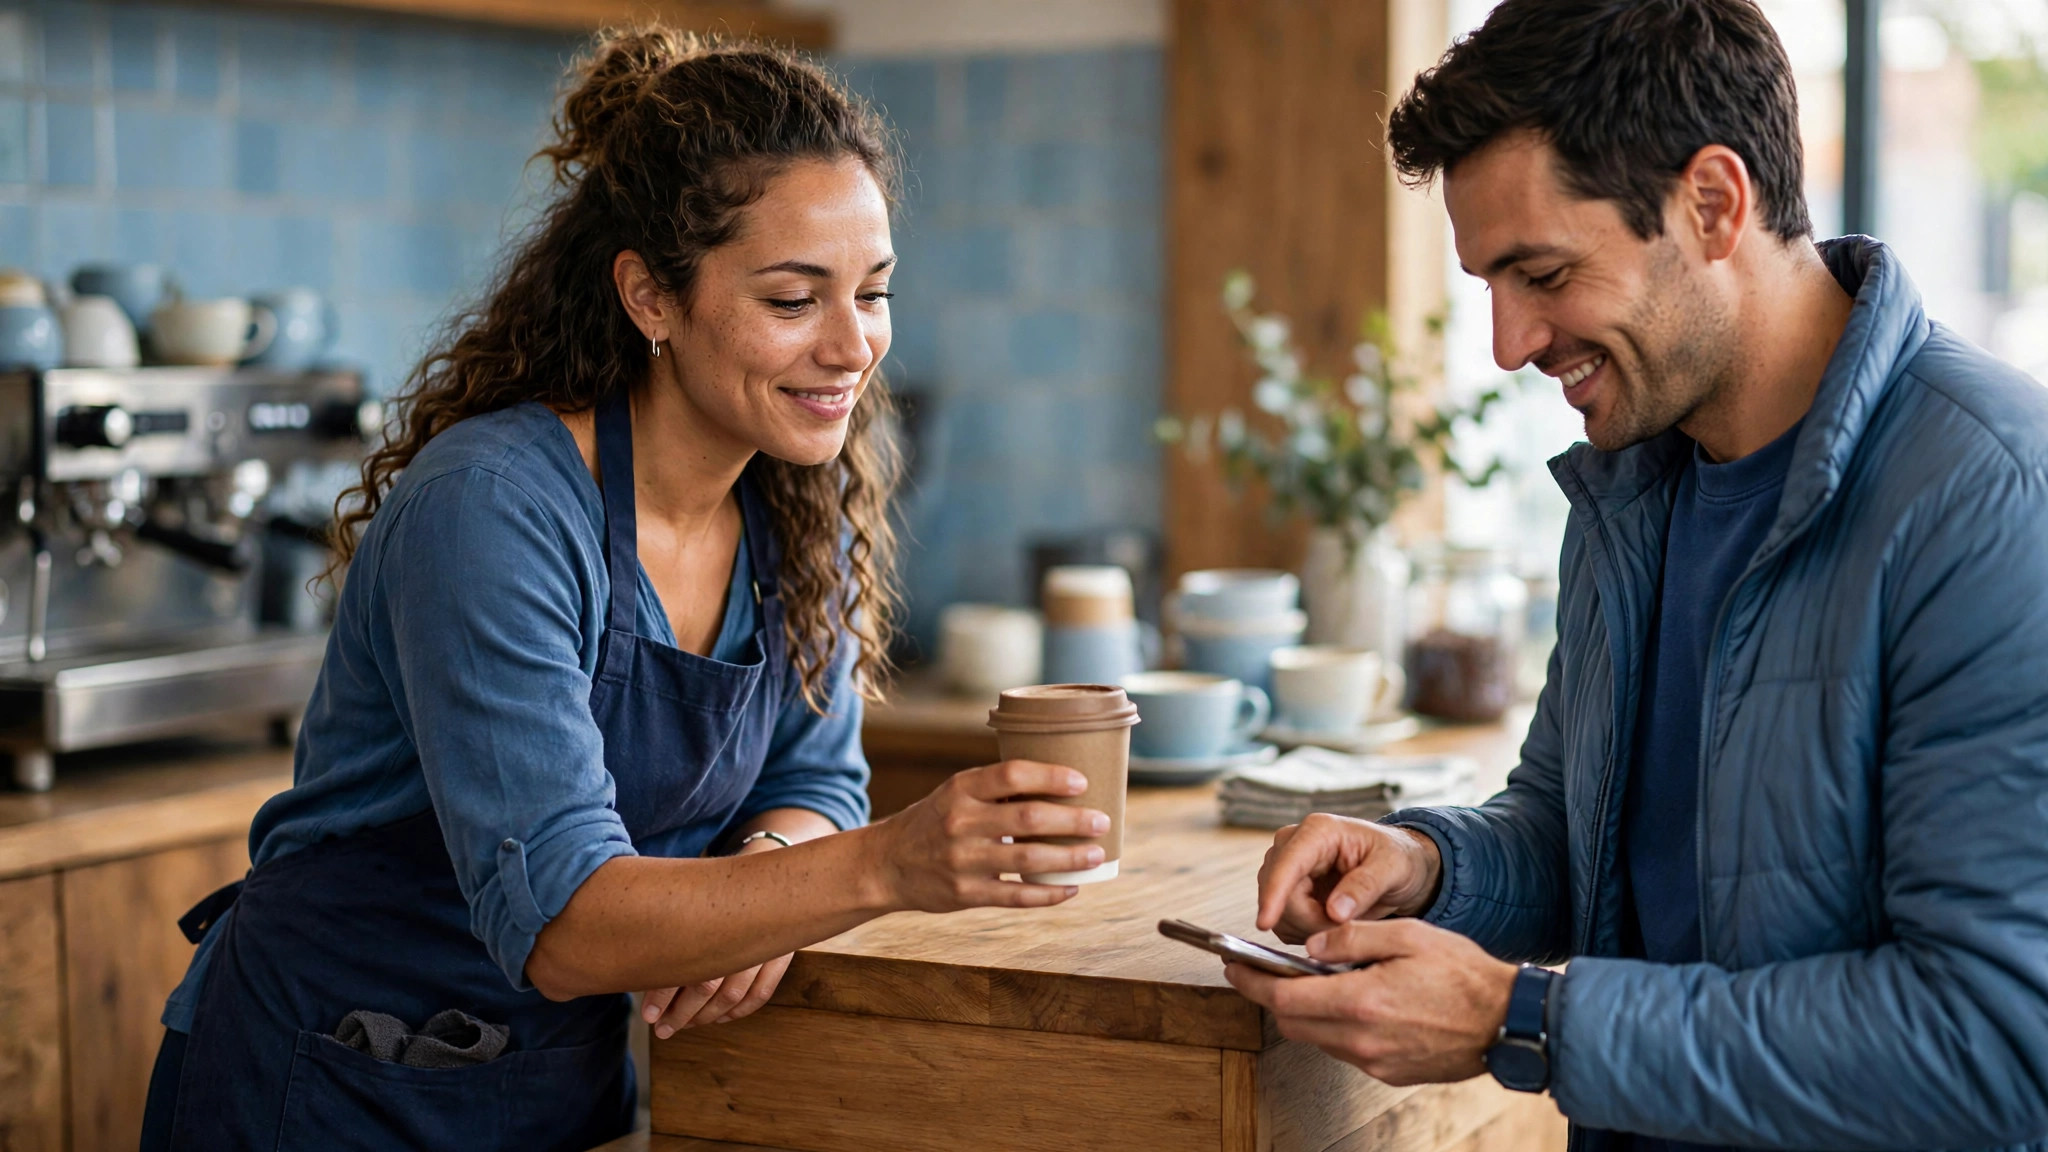
Barista handing a takeaway coffee to a customer paying by phone at a coffee shop counter

Why this guide exists

A coffee shop takes money in more ways than almost any other small business — counter cards, website orders, delivery apps and digital tips, all at once. When the account behind those payments is verified and the setup is simple, the money arrives on schedule and the records take care of themselves. When it is not, the shop learns about the problem at the worst possible moment. This guide covers the setup, the daily routine, and the fixes for the problems that actually happen.

Why a coffee shop needs a verified account

A coffee shop's register never closes — the line at the counter, the phone orders, and the tips jar all run on the same payout rails. A customer orders a latte from the sidewalk on your own website, another pre-orders a dozen pastries for the office through a delivery app, and a regular leaves a two-dollar tip on a card payment. Each of those payments travels through a different channel, but they all have to land in the same bank account, on the same schedule, with records clean enough to hand to an accountant.

That is what a verified account gives a coffee shop: one identity that every platform trusts. Verification confirms the business name, the owner, the tax ID and the payout bank, so platforms release money on schedule instead of holding it for extra checks. An unverified account can take orders for weeks and then freeze a payout at the worst possible moment — right before rent is due or the day before a big catering order needs supplies.

Verification also protects the shop's reputation. Customers who pay online expect the charge on their statement to show a recognisable business name. When the name matches the shop on the sign outside, chargebacks fall and regulars keep ordering. When it does not match, customers call their bank, and the shop pays the dispute fee.

One account, several money streams

Most coffee shops take money in at least four ways: card payments at the counter, online orders on their own website, orders through delivery apps, and digital tips. The simplest setup is one verified business account that receives all of them, with the payout bank set once and left alone. Changing the payout bank in the middle of a busy week is one of the most common reasons payouts get delayed, because many platforms put a short hold on the first payout after a bank change.

Keep the streams separate in your records even though they share one account. Tag every payout by channel — counter, website, delivery app — so that when a payout looks short, you can tell in minutes whether the gap is a delivery app fee, a refund, or a genuine problem. A simple spreadsheet with one row per payout and one column per channel is enough for most small shops.

Use the business's legal name everywhere, exactly as it appears on the tax paperwork. The name on the account, the name on the payout bank, and the name on the business registration should match character for character. A mismatch as small as "Coffee Co." on one platform and "Coffee Company" on another is enough for a platform to ask for extra documents before releasing a payout.

Tips: collecting them fairly and paying them out

Digital tips are now a meaningful part of barista pay, and they need the same care as any other money. The first decision is how tips are pooled. Some shops pool all tips and split them by hours worked; others let each barista keep the tips from their own shifts. Either system works, but it has to be written down, posted where staff can see it, and followed the same way every week. Nothing erodes trust faster than a tip pool that changes without explanation.

The second decision is when tips reach staff. Some platforms pay tips out with the regular payout on a daily or weekly schedule; others hold them for a short period first. Learn your platform's schedule before the first busy weekend, and tell the team what to expect. A barista who expects tips on Friday and gets them on Monday will assume something went wrong, even when nothing did.

Keep a tip log that matches the platform's own numbers. Once a week, compare the tips the platform reports with the tips your point-of-sale system reports. Small differences are usually timing — a tip recorded on Sunday night may not appear in the payout until Tuesday. A difference that grows week after week is a setup problem worth fixing before it becomes a dispute with staff.

The daily routine that keeps payouts on time

A five-minute routine at the end of each day prevents most payout surprises. First, check that today's online orders match today's expected payout. If the numbers are close, move on. If they are far apart, look for the usual causes: a refund you forgot, a delivery app fee, or a payout that is simply scheduled for tomorrow. Second, glance at the payout schedule itself — most platforms show the next payout date and amount on the dashboard. Third, check for any message from the platform asking for a document or an update. Platforms often ask for a refreshed ID or a new tax form with a deadline attached, and a missed deadline can pause payouts.

Once a month, do a longer check. Reconcile the month's payouts against the bank statement line by line. Confirm the payout bank is still the right one and that the card on file for platform fees has not expired. Update the business address and phone number on every platform if anything has changed — a move to a new location or a new phone number is a common trigger for a verification review, and updating the details yourself is far easier than answering a review after the fact.

Keep the account's recovery details current as well. The recovery email and phone number should belong to the owner, not to a former employee or a shared inbox nobody checks. If the owner changes their phone number, update it on every platform the same week. A locked-out owner with an outdated recovery phone can lose days of access to their own money.

Common problems and how to fix them

A payout that arrives late is the most common scare, and it usually has a boring explanation. Bank holidays push payouts back by a day or two, and the first payout after a bank change is often held for a short review. Check the platform's payout schedule and any notices before contacting support — most delays resolve themselves within one business day. If a payout is more than two business days late with no notice, contact support with the payout date, the expected amount, and the last four digits of the payout bank so they can trace it without a long back-and-forth.

A tip that never appears is usually a settings problem rather than a lost payment. Check that tipping is enabled on every channel where you take orders, and that the tip settings on the website match the tip settings at the counter. A customer who is never offered a tip prompt cannot leave one, and a shop that only enables tips on one channel will see lower tip totals than it should.

A name mismatch hold happens when the name on the account does not match the name on the payout bank or the tax paperwork. Fix it by updating the weaker side to match the legal documents — do not try to change the legal name on the account to match a nickname. If the platform asks for documents, send a clear scan of exactly what it asks for, and nothing extra. Sending the wrong document restarts the review clock.

An account review notice is not a punishment. Platforms review accounts when something changes — a new location, a sudden jump in order volume, or a new payout bank. Answer it calmly, send what is asked for, and keep taking orders while you wait. The review is the platform confirming that the business behind the account is the business it verified in the first place.

Keeping records clean for tax season

A coffee shop's payout records are also its tax records, so the same habits that keep payouts flowing keep tax season simple. Save every monthly platform statement, and keep them in one folder — digital or paper — organised by month. When the accountant asks for the year's sales, the folder should answer the question without a week of digging.

Separate business money from personal money completely. The payout bank should be a business account, and the owner's personal spending should never pass through it. Mixing the two makes every payout harder to explain and turns a simple tax return into a reconciliation project.

Finally, write down the shop's account setup in one place: which platforms you use, which bank each one pays into, who can log in, and where the recovery details live. If the owner is away or a manager needs to fix a payout problem, that document saves hours. Review it twice a year, and update it the same day anything changes. A coffee shop runs on routine — and the payment routine deserves the same care as the opening routine.

First-week setup checklist

  • Verify the business name, owner identity and tax ID on every platform before taking the first online order.
  • Set the payout bank once, confirm the first test payout arrives, then leave the bank details alone.
  • Enable tipping on every channel — counter, website and delivery apps — with the same tip options.
  • Write down the tip-pool rule, post it for staff, and follow it the same way every week.
  • Save the recovery email and phone number in the owner's name, and confirm both work.
  • Create one folder for monthly platform statements, organised by month from day one.

Weekly payout habits

  • Compare today's orders with the expected payout and note any gap the same day.
  • Check the next payout date and amount on the platform dashboard.
  • Read any platform message asking for a document or an update before its deadline.
  • Compare the platform's tip total with the point-of-sale tip total once a week.
  • Confirm the payout bank and the card on file for platform fees are still current.

Warning signs worth fixing now

  • A platform asks for your login password or 2FA code by email or chat — real platforms never do.
  • A payout is held with no message and no date — check the dashboard first, then contact support.
  • Tips are enabled at the counter but not on the website — you are losing tips on every online order.
  • The business name on the account does not match the name on the payout bank.
  • The recovery phone belongs to a former employee or a number nobody answers.
  • Monthly statements are scattered across inboxes instead of saved in one folder.
  • A payout bank change is made on a Friday before a busy weekend.

Real verification

Business name, owner identity and tax ID confirmed once, so payouts release on schedule.

One payout bank

A single verified payout bank for every channel — set it once and leave it alone.

Clean records

Monthly statements saved in one folder, ready for the accountant without a week of digging.

Ready to get your shop verified?

Every account in our catalog runs through the same checks before it reaches you. Ask us anything before you order.